Ever feel like your money simply vanishes into thin air by the third week of the month? You check your account balance, squint at the screen, and wonder where that buffer went. It usually is not a single giant purchase that drains your balance. It is the steady drip of micro-transactions, small conveniences, and recurring monthly charges that quietly sap your bottom line.
Recent data shows that average household expenditures hover around $6,545 every single month.¹ That is more than $78,000 a year, with basics like shelter, transportation, and food eating up over 60% of take-home pay. At the same time, Federal Reserve studies show that 37% of American adults cannot cover a surprise $400 emergency using cash or an equivalent safety net.² Toss in average credit card interest rates floating near 24%, and carrying even a modest balance becomes painfully expensive.³
The good news? You do not have to live on instant noodles or cancel every fun outing to fix your cash flow. Taking control of your day-to-day spending is about hunting down silent leaks and redirecting that cash back to your personal goals.
The Art of Strategic Shopping
Smart shopping comes down to adding just enough friction to outsmart your impulses. Retailers spend billions designing frictionless checkout flows so you can buy items without thinking. You can flip the script with a few deliberate habits.
• The 48-hour cart rule: When browsing online, drop non-needed items into your cart and walk away for two full days. This cooling-off period breaks the emotional dopamine loop that triggers impulse buying. Most of the time, you will realize you did not actually need the item.
• Remove stored credentials: Delete saved credit cards from your browser and disconnect one-click checkout options on your phone. Forcing yourself to get off the couch and type in 16 card numbers creates physical friction, giving your rational brain time to intervene.
• Reverse meal planning: Most people find a recipe and buy ten ingredients they will never use again. Instead, look inside your pantry and freezer first. Build your weekly menu around what you already own, then buy only the few fresh perishables you need to complete those meals.
• Run an eat-down day: Designate one evening a week to cook meals using only leftovers and whatever items sit close to expiration. Food waste costs the typical household between $1,500 and $2,400 annually, so cleaning out the fridge literally pays you back.
Finding Consumer Savings Through Automation and Rewards
Why let recurring payments drain your accounts without working for you? Automating your savings routine helps you keep more money with minimal ongoing effort.
• Rotate your subscriptions: People drastically underestimate their monthly subscription costs, believing they spend around $86 while actual totals frequently run past $200. Instead of paying for five streaming platforms at once, pick one service per month. Watch your favorite shows, cancel it, and switch to a different platform the next month.
• Drop down to ad tiers: If you want steady access to favorite streaming libraries, downgrade from premium ad-free tiers to ad-supported plans. Making that shift across two or three platforms easily pockets $60 to $120 a year per service.
• Collect automated rewards: Use cash-back portals and credit card reward categories for groceries, gas, and utility bills you already pay anyway. Just remember to pay the balance in full each month so high interest rates do not erase your rewards.
• Schedule quarterly audits: Set a recurring calendar reminder every three months to scan your bank statements for zombie subscriptions, gym memberships you forgot about, or apps you stopped using.
Reducing Routine Expenses Without Feeling the Pinch
Trimming regular expenses does not require sacrificing quality. It is about spotting where markup exists solely for branding or consumer inertia.
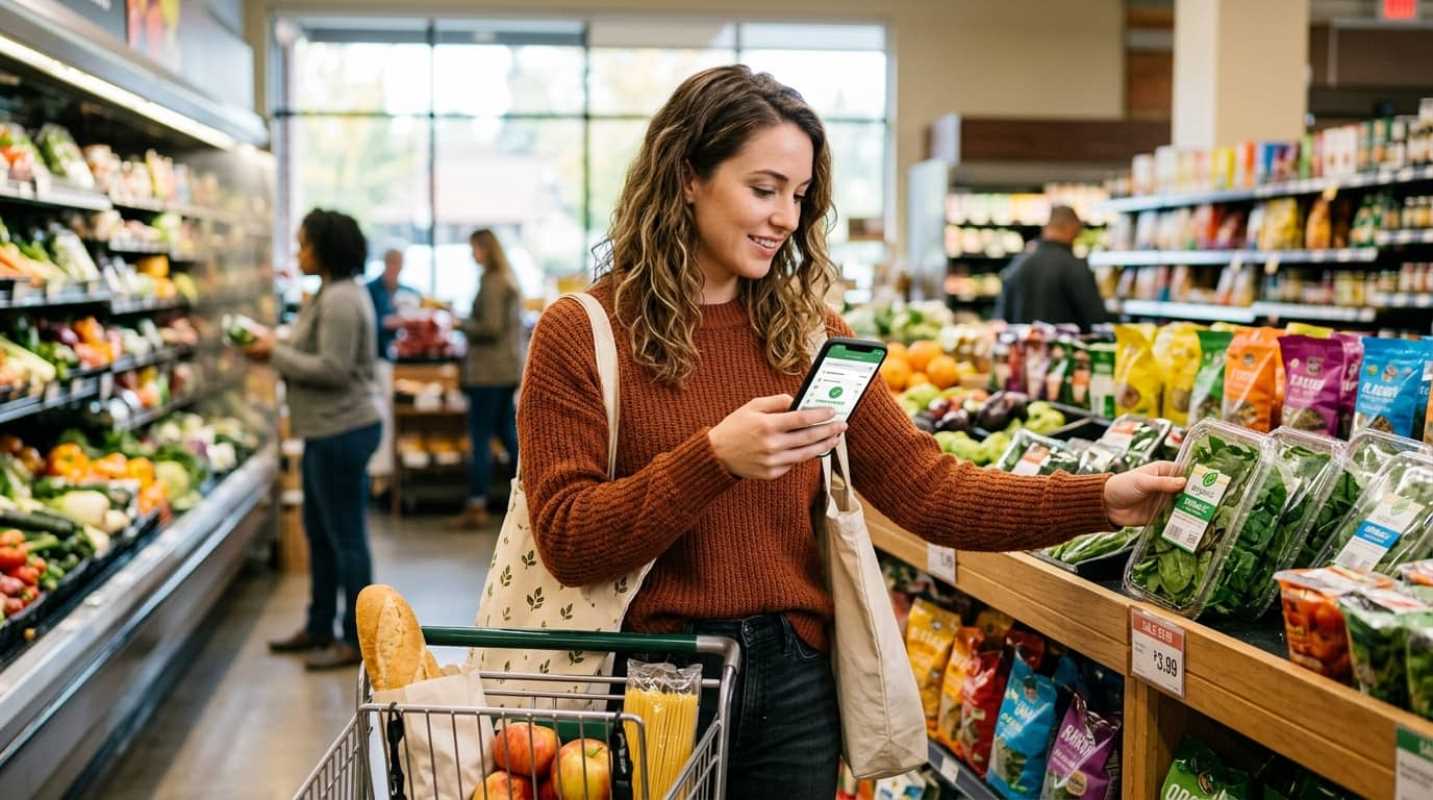
Take grocery shopping as an example. Switching from name-brand items to store brands can lower your grocery bill by 20% to 70%. In categories like baking staples, canned beans, cereals, and beverages, private-label products are often produced in the exact same processing facilities as the name brands. You are paying a premium just for fancy packaging and television commercials.
Your recurring monthly bills offer another huge area for fast wins.
• Call your credit card issuer: If you carry a revolving balance, pick up the phone and ask for a lower APR. Over 80% of cardholders who call and ask receive a rate reduction, with average drops of over six percentage points. That single call can save you well over a thousand dollars in annual interest charges.
• Shop for your auto insurance: Car insurance rates have spiked significantly in recent years. Calling three to five competing providers or working with an independent broker at renewal time can unlock serious savings, often over $1,000 annually. You can also bundle your auto coverage with renters or homeowners insurance for a reliable 10% to 20% discount.
• Ditch the major mobile carriers: You do not need to pay $90 a line to stay connected. Mobile virtual network operators run on the exact same nationwide cell towers as major providers, but they cost between $15 and $30 per month.
Building Sustainable Financial Habits
When you add up these adjustments, the numbers multiply quickly. Cutting food waste puts around $1,500 back in your pocket. Rotating subscriptions frees up hundreds more. Shopping for your insurance and switching to store brands can easily save another couple of thousand dollars every year.
Saving money on everyday purchases is a practical form of investing in your peace of mind. Every dollar you stop leaking into forgotten subscriptions or inflated brand markups is a dollar you can put toward an emergency fund, travel, or retirement.
Do not try to overhaul your entire financial life in an afternoon. Pick just one category to tackle this week. Clean out your pantry for an eat-down dinner, uncheck your browser autofill, or call a provider to renegotiate a bill. Win that first small victory, feel the momentum, and build from there.
Sources:
1. Average American Monthly Expenses and Bills
https://www.chase.com/personal/banking/education/budgeting-saving/average-american-monthly-expenses-and-bills
2. Economic Well-Being of U.S. Households
https://www.federalreserve.gov/publications/2025-economic-well-being-of-us-households-in-2024-savings-and-investments.htm
3. Average Credit Card Interest Rate in America
https://www.lendingtree.com/credit-cards/study/average-credit-card-interest-rate-in-america/
*This article on Travado is for informational and educational purposes only. Readers are encouraged to consult qualified professionals and verify details with official sources before making decisions. This content does not constitute professional advice.*